
The Conservation of MEV – Why Ordering Value Can’t Be Designed Away, Only Hidden
by Jascha Samadi – September 28, 2026
In physics, energy cannot be destroyed – it only changes form. Transaction ordering has the same property. Wherever a ledger executes transactions against valuable shared state, the order of execution carries economic value – and that value is conserved across every architecture we know of. It can be auctioned, concealed, burned, or renamed, but it does not go away. Ethereum turned it into an open market. Permissioned networks like Canton moved it behind contracts and NDAs. Traditional finance carried it for a century under names like payment for order flow and last look. Hyperliquid recently began burning it.
We have spent much of the past years working in and around the transaction supply chain – the path a transaction travels between the click in a wallet and its final position in a block, and the market structure that has assembled itself around that path. This essay is the structural view that work has left us with. It traces the conservation of ordering value across four regimes (open market – private ledger – regulated intermediary – public auction). The interesting question was never “MEV or no MEV.” It is whether the price of ordering is public or hidden. And traditional finance’s enforcement record shows in detail what happens when the value is denied rather than priced.
This essay continues our Block Building series, which so far covered a primer of the blockspace market, the demand side and the supply side of Ethereum block building since 2024.
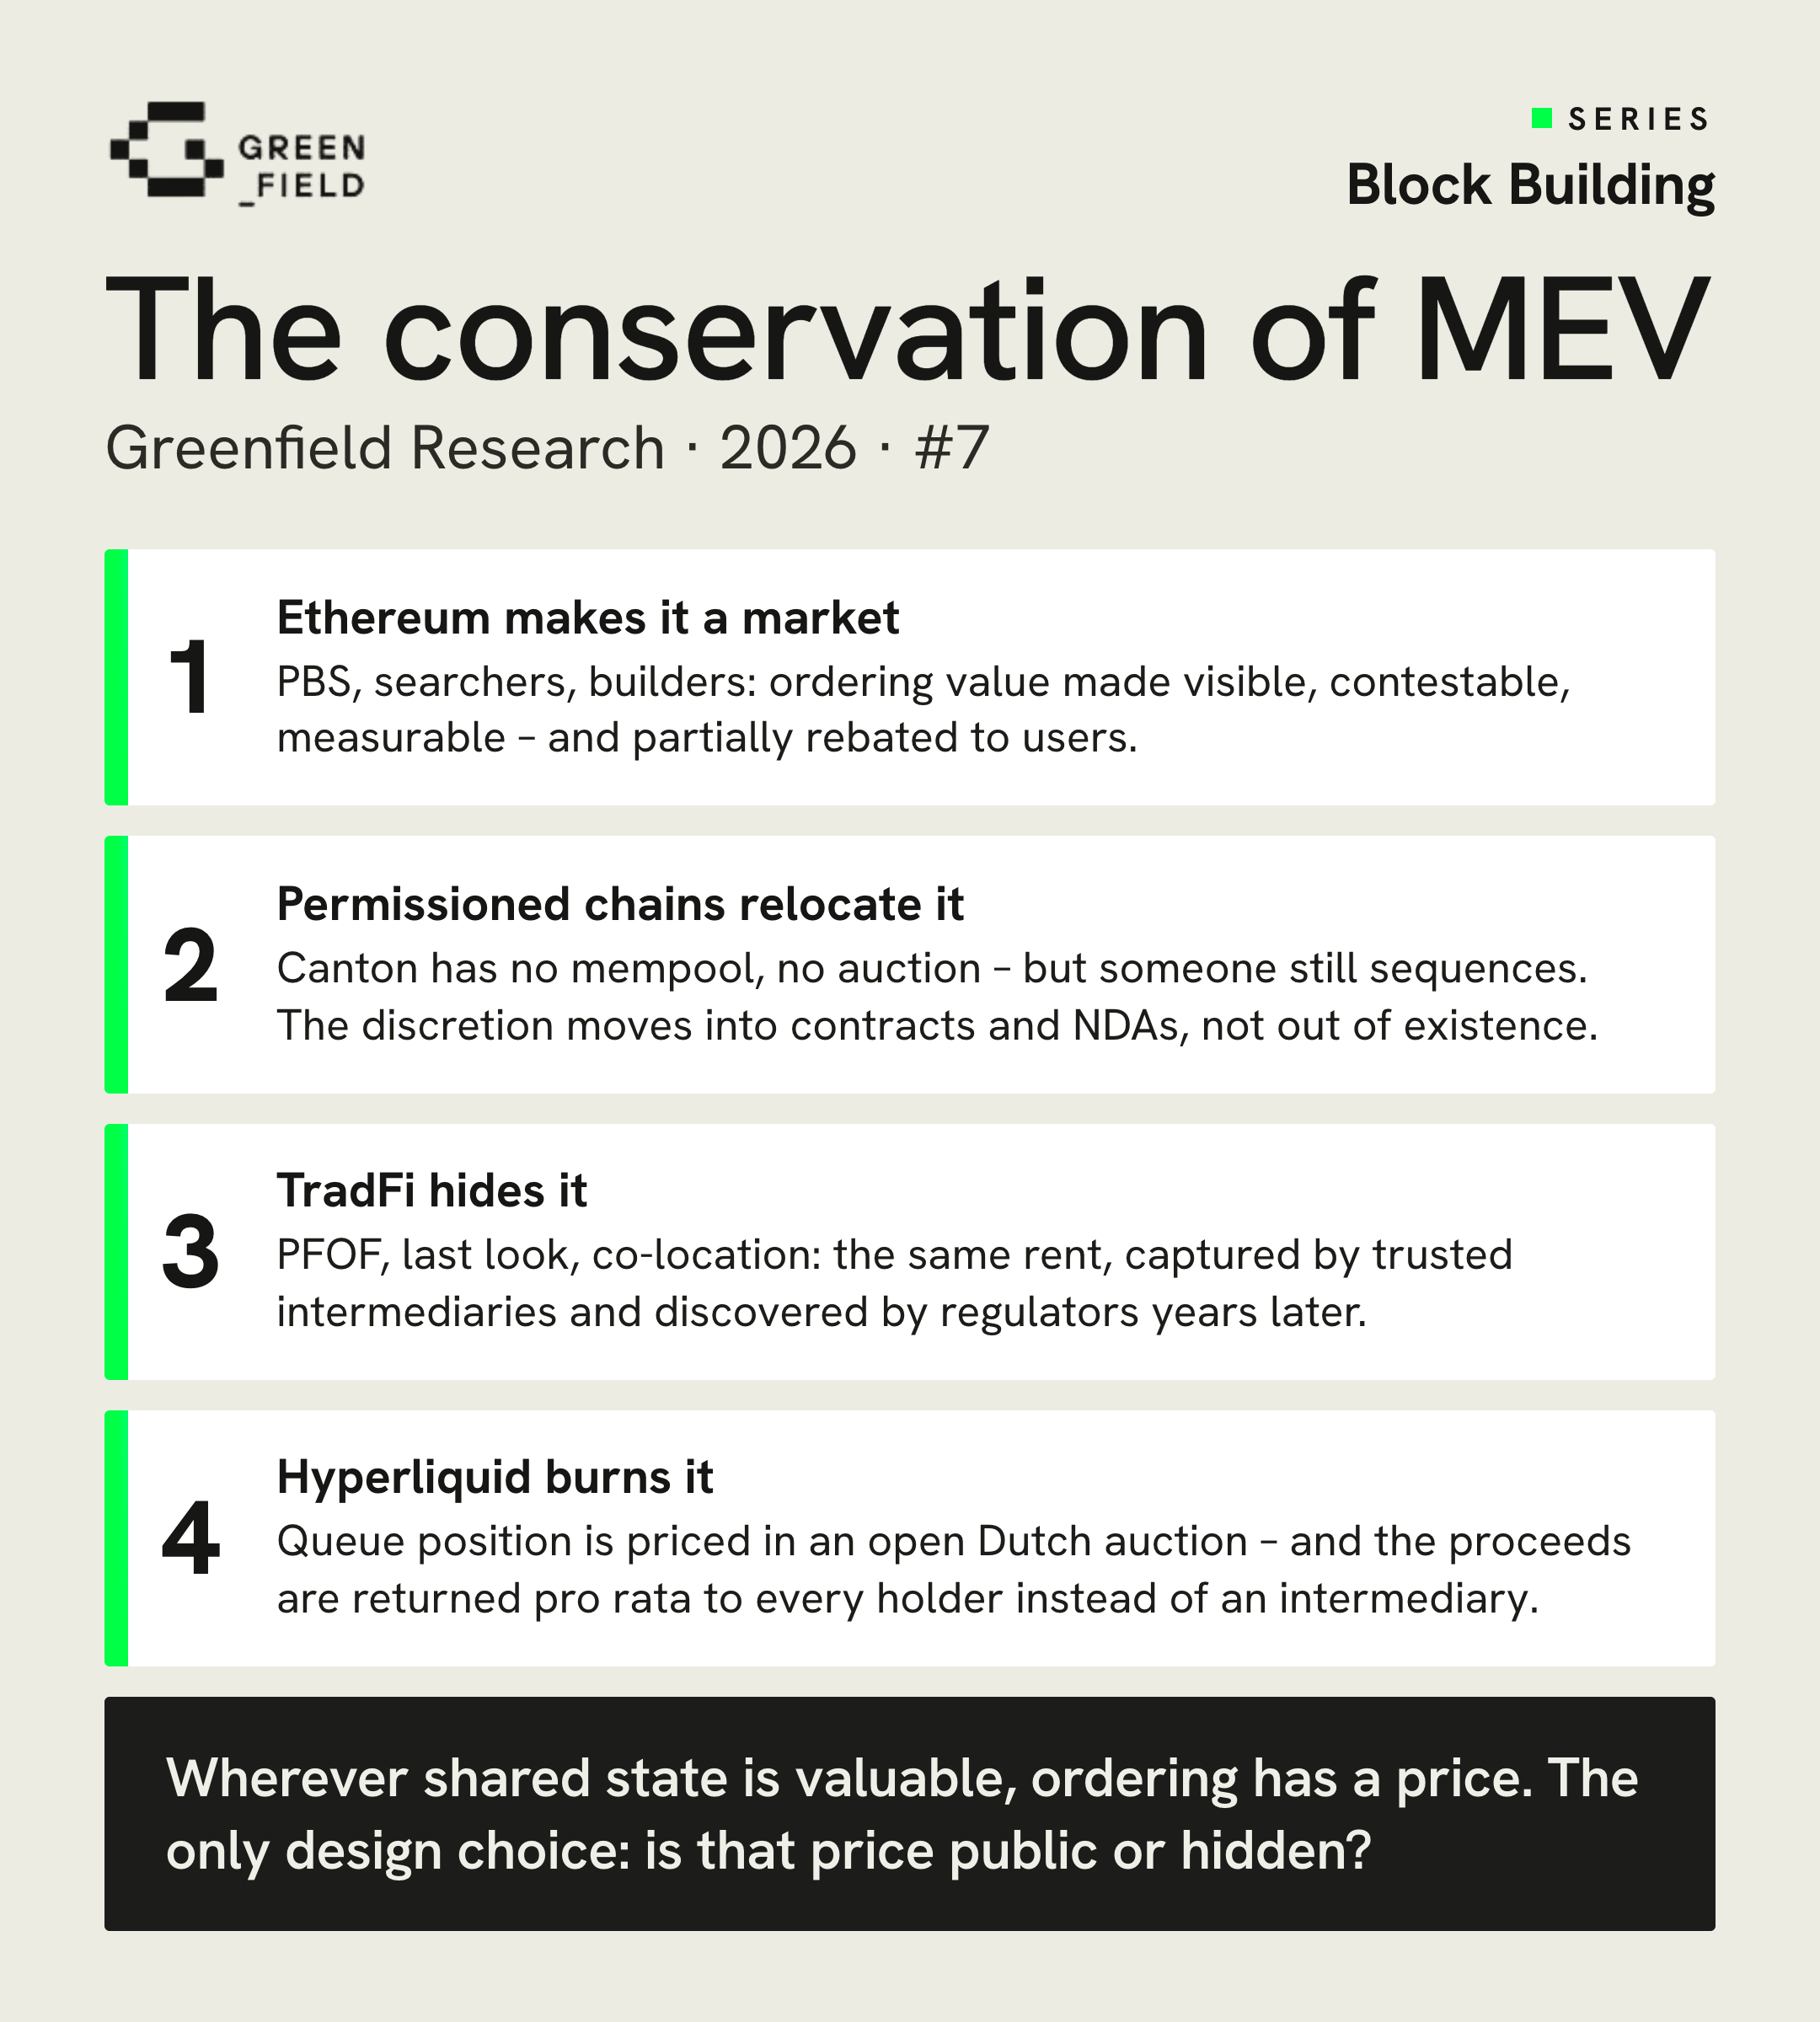
The open market: Ethereum prices ordering value
A public permissionless blockchain rests on a small number of foundational design choices:
- Anyone can run a node and independently verify the network’s history.
- Anyone can submit a transaction.
- Participation in consensus – the right to produce blocks and extend the chain – is open, acquired through capital or work rather than granted by a gatekeeper.
- Underpinning all of this is the most consequential choice: every participant replicates the same ledger. There is a single global state visible to all, and every node re-executes every transaction to confirm that the rules were followed.
Global shared state is what makes these systems more than just a distributed database. Since every application lives in the same state machine, any contract can read from and synchronously compose with any other. A lending protocol can consume a price oracle it has never coordinated with, accept collateral tokens issued by a third party, and be wrapped by an aggregator nobody approved – all within a single atomic transaction. Integration is an import statement rather than a business-development negotiation. This property – permissionless composability atop a commonly verifiable state – is the source of most of what is genuinely novel in onchain finance: open verifiability, credible neutrality, and markets that unaffiliated parties can assemble at the speed of deployment.
The same choice carries a second, less-advertised implication. If everyone shares a single state, transactions must be applied to it in some order, and because many transactions touch the same state, the order can change the outcome. Two trades against the same liquidity pool do not commute: the one sequenced first receives the better price. A liquidation is available to exactly one caller: whoever arrives first. An arbitrage exists for exactly one transaction: the one placed ahead of the rest. Position in the sequence is an access right to economic opportunity, and access rights that are scarce and valuable do not remain unpriced for long.
Ethereum is the clearest case study in what happens once that value becomes legible. An industrial supply chain (searchers, builders, relays, validators → see also our primer on Ethereum’s blockspace market) assembled itself around the path between a user’s wallet and a finalized block. Searchers scan the public mempool and the state for extractable opportunities – arbitrage across pools, liquidations, and, at the predatory end, sandwich trades around visible user orders. Builders assemble candidate blocks. They pack and sequence transactions and bundles to maximize a block’s total value. Under proposer-builder separation (PBS), validators no longer construct blocks themselves; they can auction the right to build to the highest-bidding builder through relays. Upstream, order flow itself has become an auctionable asset, with wallets and applications selling the right to interact with their users’ transactions.
It is common to describe this machinery as parasitic, and some of its parts might even be. The more precise description is that PBS is what a market for a scarce resource looks like once the resource is acknowledged.
Ordering was always valuable; Ethereum’s architecture made that value visible, contestable, and measurable.
The research agenda that followed – order flow auctions, MEV rebates that return extraction to the users whose transactions created it, encrypted mempools, batch auctions – is not an attempt to deny the phenomenon. It is an attempt to govern it: to decide deliberately who captures ordering value and how much of it flows back to users.
The alternative approach is to remove the preconditions for a public ordering market altogether. That permissioned approach also now has trillions of dollars of monthly volume behind it.
The private ledger:
Canton removes the market, not the value
The most substantial permissioned network in production inverts every design choice above – deliberately and coherently – yet what it eliminates is the market for ordering, not the discretion over it. Canton has no global state and no global transparency. It is structured as a network of networks: each participant runs a validator that holds only the contracts to which it is a party, and data propagates strictly on a need-to-know basis. The privacy model extends inside individual transactions. Sub-transaction privacy means that even counterparties to one leg of an atomic transaction do not see the other legs: a bank settling the bond leg of a delivery-versus-payment trade does not learn the commission terms on a different leg of the same atomic commit. There is no public mempool – pending transactions are never broadcast, only delivered to their stakeholders. And the sequencing layer is blind: synchronizer operators order encrypted confirmations without seeing transaction contents.
Canton’s position on MEV follows from these choices almost mechanically, resting on four mechanisms:
- There is no mempool to snipe: transactions are never broadcast publicly, so the raw material of front-running – visible pending order flow – does not exist at the network layer.
- Sequencing is blind: an operator cannot trade ahead of what it cannot read.
- There is no ordering market: no builder or searcher auction, no priority-fee bidding for position, no PBS supply chain – sequencing is a utility function performed by identified, contracted institutions with legal accountability rather than by pseudonymous actors.
- Ordering rules live at the application level: they are written into the smart-contract logic itself, so exchange-style fairness rules such as price-time priority are enforceable by construction rather than dependent on validator behavior.
The adoption behind this design is substantial by any standard. Broadridge’s Distributed Ledger Repo platform settles on the order of $8–9T of repo volume per month – roughly $354B a day – on Canton infrastructure, making it the largest settlement platform for tokenized real-world assets (RWA) in operation. Public trackers attribute roughly $345B of represented asset value to the network, and aggregate claimed throughput is near $9T monthly. The fit with the flagship use case is genuine: interbank repo and collateral markets are precisely where privacy, permissioning, and finality-with-recourse matter more than censorship resistance. No bank will broadcast its funding positions to a public mempool – real-time visibility into who is raising overnight cash is not transparency but a run accelerant – and no regulator will license critical market infrastructure where a software fault is an unrecoverable loss.
We consider the bifurcation to be rather permanent: permissioned networks of this kind are likely to remain very successful for institutional back-end workflows – settlement, collateral mobility, post-trade – where participants are a known set, trades are pre-negotiated, and confidentiality and recourse are requirements rather than preferences. That market is large, and Canton is winning it on the merits of its design. The question at hand is narrower: whether this architecture eliminates MEV or does something more familiar with it.
The structural observation is that somebody still sequences.
On Canton, ordering discretion has not disappeared; it has been relocated – to synchronizer operators on the public layer, and to single firms on the private synchronizers where the large majority of today’s volume actually settles.
The discretion still exists; it is non-contestable, non-observable, and governed by NDAs and terms of service rather than eliminated by cryptography. What a permissioned network can rigorously claim under the heading of “no MEV” is therefore narrower than the phrase suggests: there is no permissionless market for MEV, and there is no public evidence of its extraction. Those are different statements, and the distance between them is where most of market-structure history lives.
The near-zero level of observed MEV on these networks also has a second explanation, alongside the design: the use cases. Canton’s flagship workflows – bilateral repo, DvP settlement of pre-agreed trades – contain almost no contested shared state. There is nothing to sandwich in a repurchase agreement whose price, size, and counterparties were fixed before the transaction reached the ledger; sequencing a queue of pre-negotiated settlements carries no economic value on any chain, under any design. The current record is therefore better described as unfalsified than as proven.
The falsifiable test arrives when such a network hosts a genuinely competitive market structure: a shared central limit order book, liquidation engines, oracle-triggered margin calls, a tokenized treasury market trading at scale. At that point, order of arrival at the synchronizer becomes economically decisive again, and the participants positioned to capture it are those with latency advantages, physical proximity, or operator relationships. The rent does not disappear. It migrates into privileged and opaque channels – preferential connectivity that never appears in a fee schedule, informational proximity that never appears anywhere. The architecture has reintroduced trusted intermediaries with sequencing discretion and reconstructed the traditional-finance trust model on a ledger.
Whether that is a stable resting place depends on the record of that trust model on precisely this problem. That record is instructive.
The regulated intermediary:
TradFi has been hiding the same rent for a century
Traditional finance ran the “trusted intermediary with sequencing discretion” model for decades; its enforcement record shows that opacity did not prevent the capture of ordering value – opacity is what made the capture profitable.
Traditional market structure has generally treated what we now call MEV as a problem of system design – something that correct rules, accountable intermediaries, and enforcement have resolved. The structural view says otherwise.
MEV is a property of valuable shared state plus sequential execution, which every trading venue possesses. On that view, traditional finance never eliminated the problem but prohibited it by rule, policed it imperfectly, and pushed the extraction into channels invisible to its victims. The enforcement record is consistent with the structural view.
Payment for order flow (PFOF) converts retail orders themselves into a monetizable asset. U.S. brokers collected roughly $3.8B in PFOF in 2021 alone – the value of seeing and internalizing flow, captured in bilateral broker-wholesaler agreements invisible to the customers whose orders were the product. Robinhood paid a $65M SEC settlement in 2020 for misrepresenting the execution quality attached to that arrangement. Dark pools, marketed to institutions as protection from predatory flow, produced a series of settlements for the opposite: Barclays paid $70M and Credit Suisse $84.5M in 2016 for misrepresenting how their pools operated, including the participation of the very high-frequency flow clients had been told was excluded, while ITG paid $20.3M in 2015 for operating an internal desk that traded on confidential client order information inside its own pool. In foreign exchange, Barclays paid $150M in 2015 over its use of “last look” – the dealer’s option to reject a trade after observing which way the price moved – and the coordinated sharing of client order information ahead of benchmark fixes cost the industry more than $10B in penalties.
The pattern across these cases is consistent. The ordering value was real. The extraction was performed by the trusted intermediary positioned in the sequence. The affected parties could not observe it in real time. And the facts surfaced only through whistleblowers and enforcement actions, years after the rents had been collected. This is the operating model that “MEV-free by design” imports onto a ledger: ordering rents adjudicated by compliance functions and discovered by regulators, rather than priced by an open market.
The public auction:
Hyperliquid burns it
The transparent alternative is not hypothetical: Hyperliquid took the same structural rent, moved it into a public auction, and directed the proceeds to the commons.
Hyperliquid’s architecture – no public mempool, ordering handled at the consensus layer – has long been described as MEV-resistant, and by the standards of mempool-based extraction, it is. An execution edge nonetheless existed, because under the structural view, one always does: priority went to whoever engineered the lowest latency. Sophisticated market makers won queue position through infrastructure optimization and network proximity – functionally, co-location. That edge existed for a long time, economically significant and available only to participants with the capital and access to build it. The rent was being captured; it simply appeared on no one’s dashboard.
In April, Hyperliquid formalized this dynamic. It introduced priority fees: open, continuously recurring Dutch auctions, denominated in $HYPE, for the two things low latency was actually purchasing – earlier sight of incoming transaction data, and earlier placement in the execution queue. The effect is measurable with unusual precision: roughly 45 milliseconds of end-to-end latency improvement per basis point of priority fee paid. An advantage that was previously implicit, private, and gated by engineering capability is now an explicit, public, continuously repriced market open to any participant.
Two properties of the mechanism are worth separating. The first is that it formalizes a paid priority tier, and that is a legitimate object of criticism – a visible tax on queue position now exists where none was established before. The relevant comparison, however, is not a market without a priority tier; it is the same tier allocated by capital expenditure and connectivity, invisibly, at a price of zero.
An explicit and priced advantage is more honest than an implicit and free one, and it is more correctable.
A visible market can be measured, debated, capped, and redesigned, while an invisible one can only be discovered after the fact.
The second property is where the proceeds go, and it is the one we consider genuinely novel in market structure. The fees are burned. The clearing price of execution priority is not paid to the venue operator, not shared with a favored counterparty, and not embedded in a bilateral agreement; it is removed from supply – economically equivalent to distributing it pro rata to every holder of the network’s asset $HYPE. The comparison with how the equivalent value flows in traditional markets is direct: co-location fees accrue to the exchange’s shareholders; payment for order flow is divided between a wholesaler and a broker under a contract the end client never sees; the informational rents of dark pools and last look accrued to whoever held the privileged seat, until enforcement recovered a fraction. Hyperliquid took the same structural rent – the value of position in a sequence – moved it into the open, allowed a permissionless auction to discover its price, and directed the proceeds to the commons.
The queue still exists; what changed is that its price is public and its economics are shared with every holder rather than settled in closed bilateral structures.
This is not a claim that ordering value has been designed away. It is the recognition that it cannot be, followed by the decision to price it in the open and redistribute the proceeds.
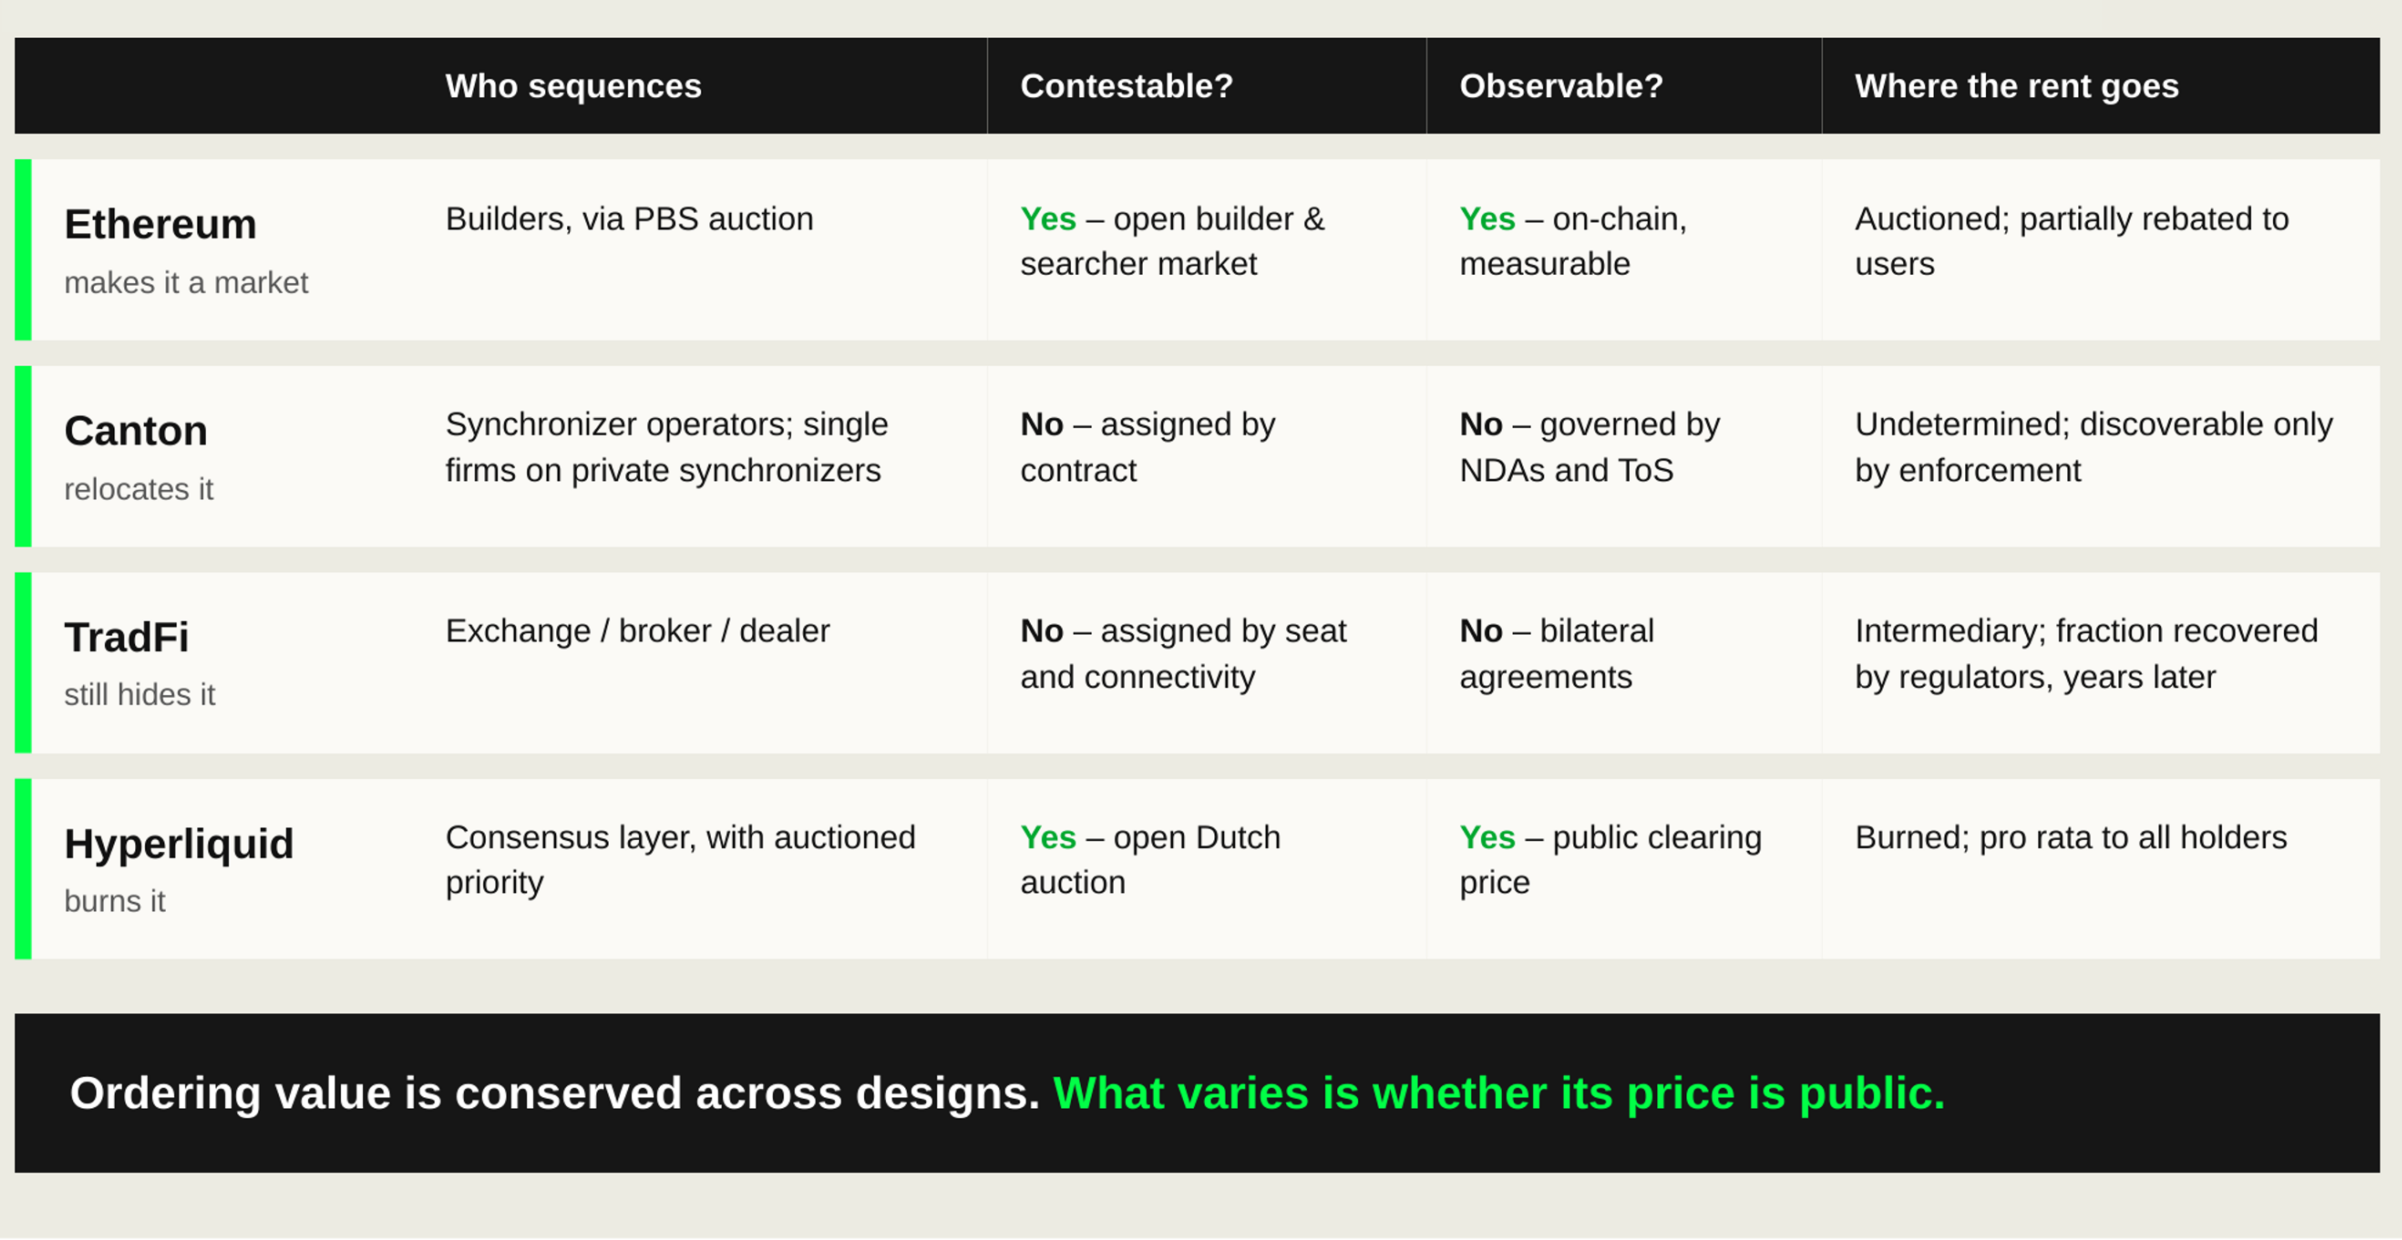
Conclusion:
What varies is whether the price is public
The useful comparison between chain designs was never “MEV versus no MEV” – every venue that sequences valuable state transitions generates ordering value as a matter of structure.
The questions that actually differentiate market designs are narrower and more answerable: who holds the ordering power; whether it is contestable or assigned; whether it is observable or hidden; and whether its rent is priced in an open market and redistributed, or captured quietly by whoever sits closest to the sequencer.
Permissioned networks answer these questions with governance – identified operators, legal accountability, and institutional assurance. For pre-negotiated settlement workflows, where ordering carries no value in the first place, that answer is adequate, and the adoption data reflects it. For genuinely competitive markets, the combined evidence of crypto’s short history and traditional finance’s long one points in one direction: ordering value that is denied tends to be captured in the dark, while ordering value that is acknowledged can be priced, audited, and returned to the market that created it. Ordering value, in this sense, is conserved across designs. What varies is whether its price is public.